Where Americans Are Actually Moving Abroad After 55
General information only — this is not immigration, tax, or financial advice. Requirements change and vary by consulate; confirm current rules with the relevant embassy or a qualified immigration attorney before making plans.
Every retirement-abroad article promises paradise and a lower cost of living. Fewer of them tell you the actual income number a consulate wants to see, or the two facts that quietly follow every American passport around the world no matter where you land. We’re covering both today.
The income thresholds, country by country
These are retirement or passive-income visa categories specifically, current for 2026. All figures are approximate and consulates can apply them differently, so treat these as the number to plan around, not the number to arrive with exactly.
Portugal — D7 Visa. Requires roughly €920 per month in stable passive income (pension, dividends, rental income) — about €11,040 a year — plus an additional 50 percent for a spouse and 30 percent per dependent child. Most consulates expect applicants to exceed the minimum with a savings buffer on top. Portugal remains one of the most popular landing spots for American retirees, thanks to English-friendly cities, a relatively low cost of living for Western Europe, and a path to citizenship — now set at 10 years of residency rather than the previous 5, following a 2026 law change.
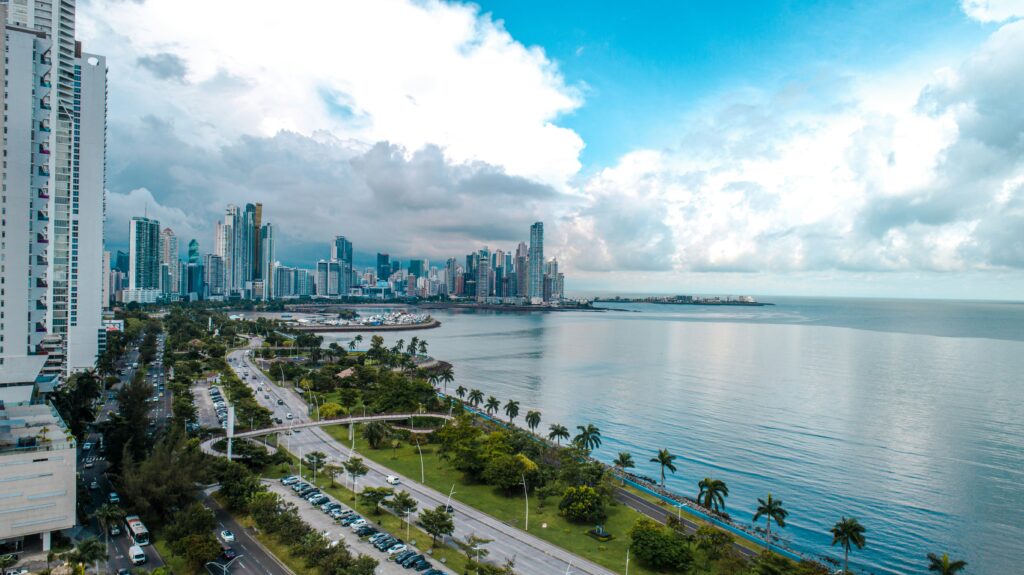
Panama — Pensionado Visa. One of the most accessible programs on this list: a guaranteed lifetime pension of at least $1,000 per month from a government, military, or qualifying private source, with $250 more per month required for each dependent. Buy at least $100,000 in Panamanian property and the required pension drops to $750 per month. The Pensionado program also comes with genuinely useful retiree discounts — on everything from medical visits to airfare to entertainment — that other countries’ programs don’t offer.
Costa Rica — Pensionado Visa. Requires a monthly pension of $1,000 or more from a single source — Social Security counts, and it’s the most common qualifying source for American applicants. Note the “single source” rule: you generally can’t combine a smaller personal pension with a spouse’s smaller pension to clear the bar: the qualifying applicant needs to hit $1,000 on their own.
Spain — Non-Lucrative Visa. Not marketed as a “retirement visa” specifically, but it’s the standard route for retirees with no intention of working in Spain. For 2026, the main applicant needs to show roughly €28,800 per year (about €2,400/month) — set at 400 percent of Spain’s IPREM index — plus comprehensive private health insurance, since retirees aren’t yet in the Spanish public system. Add roughly €7,200 per year for each additional family member.
Greece — FIP Visa (Financially Independent Person). The highest income bar on this list: roughly €3,500 per month, or €42,000 per year, in passive income, rising 20 percent for a spouse and 15 percent per dependent child. In exchange, Greece offers a notable tax incentive some retirees find worth the higher entry bar: a flat 7 percent tax rate on foreign pension income for up to 15 years for qualifying new tax residents.
Uruguay — Pensionado Visa. Requires $1,500 per month in foreign pension income for a single applicant, or $2,500 per month for a couple, with no minimum age requirement. It also requires a $100,000 investment — a home purchase or Uruguayan government bonds — held for ten years. Uruguay is less discussed in American retirement circles than the others here, but it offers political stability and a temperate climate that draws comparisons to the U.S. Pacific Northwest.
Mexico — Temporary Resident Visa. The one entry on this list where the rules genuinely tightened. Effective January 1, 2026, the income requirement for a Temporary Resident visa jumped to roughly $4,400 per month in verifiable income — up sharply from about $2,800/month in 2025 — or alternatively, an average savings/investment balance of roughly $74,000 over the trailing twelve months. Mexico remains the single most popular retirement destination for Americans by sheer numbers, largely because of proximity and long-established expat communities, but 2026 applicants should not assume last year’s numbers still apply — this is the country where checking the current figure before you plan matters most.
The two things nobody mentions in the brochure
Every one of these programs gets marketed around sunshine and cost of living. Two facts get left out of almost every pitch, and both of them matter more than the income threshold.
Medicare doesn’t follow you
We covered this in an earlier piece on healthcare abroad, but it bears repeating here because it’s the single most consequential gap in most people’s planning: Original Medicare generally does not cover care you receive outside the United States. There are a few narrow exceptions — certain emergencies where a foreign hospital is genuinely closer than a U.S. one, some Canada-adjacent travel, and specific cruise-ship scenarios within six hours of a U.S. port — but as a rule, if you need care abroad, you are paying for it yourself, and that includes prescription medications. Some Medicare Advantage plans have begun offering optional domestic “travel” add-ons in 2027, but these do not extend to living abroad long-term, and none of the retirement-visa countries above are covered by Original Medicare as a matter of course.
The practical fix retirees actually use: private international health insurance purchased in the destination country (often required for the visa itself, as with Spain), plus keeping Medicare Part B active if you plan to return to the U.S. periodically — because dropping it to save the premium can trigger the same late-enrollment penalty covered in this week’s Medicare piece if you ever need to re-enroll.
The IRS doesn’t let go
The United States taxes citizens on worldwide income no matter where they live — one of only a small handful of countries that taxes based on citizenship rather than residency. Moving to Portugal or Panama does not end your U.S. tax filing obligation; it adds a second country’s rules on top of it.
The tool most people reach for is the Foreign Earned Income Exclusion, which for 2026 lets you exclude up to $132,900 of qualifying income from U.S. tax. Here’s the detail that trips up retirees specifically: the exclusion only applies to earned income — wages and self-employment income. Pensions, Social Security, dividends, rental income, and capital gains — the exact income sources that qualify you for most of these visas in the first place — are not earned income and get no benefit from this exclusion. Retirees living on Social Security and a pension are typically still filing (and often still owing something to) the IRS every year, offset in some cases by a foreign tax credit for taxes paid to the host country, and by any applicable tax treaty. This is genuinely complicated enough that a cross-border tax professional, not a blog post, should be the one confirming your specific numbers before you move.
The question to ask before any of this
Before signing a lease, buying property, or committing to a visa application: have you rented in the country for a full year first?
Every one of these destinations looks different in its rainy season than its brochure season, and the difference between a two-week vacation and a Tuesday in February when you don’t speak the language and your regular doctor is 4,000 miles away is larger than most people expect walking in. A one-year rental costs a fraction of what unwinding a bad property purchase costs, and it’s the single piece of advice that shows up in nearly every honest account from people who’ve actually done this — as opposed to the ones selling the dream.
Go be bold!
This article is for general informational purposes and does not constitute immigration, tax, or financial advice. Visa requirements, income thresholds, and tax rules change and are applied differently by individual consulates; verify current requirements directly with the relevant embassy or consulate, and consult a qualified immigration attorney and a cross-border tax professional before making a decision.